Will Your Money Last
as Long as You Do?
Safeguard your longevity with guaranteed, inflation-proof retirement cash flow.
Outliving your wealth is the silent crisis of modern retirement. We design resilient capital structures that protect your
principal, optimize tax efficiency, and generate dependable income for life.
Strictly confidential : No product push : Tailored bespoke advisory
CRITICAL REALITY CHECK
The Biggest Risk Is
Running Out of Income.
Most professionals spend 30 years building a retirement corpus, only to realize that a lump sum without an inflation-proof cash-flow blueprint dissolves twice as fast as anticipated. With longevity now stretching retirements beyond 30 years and medical inflation compounding at double digits, the fear of outliving your wealth is not unwarranted : it is inevitable without strategic structural planning.
Will your accumulated wealth sustain your current lifestyle against 7% annual inflation for 30+ years?
How quickly would your family's monthly cash flow collapse if a critical illness requires prolonged private care?
Could a sharp 20% equity drawdown in your first three years of retirement irreversibly deplete your capital?
Are you willing to face the quiet emotional humiliation of depending on your children for everyday expenses?
These are sobering questions, but facing them today is the only guaranteed way to insulate your dignity, lifestyle, and financial autonomy tomorrow.
Takes 2 minutes : 100% Confidential : Zero sales pressure
A NEW CHAPTER OF CLARITY
Your Retirement Should Be a
New Beginning.
Retirement is not an end to achievement, but the beginning of boundless autonomy. Leave uncertainty behind
and embrace the quiet luxury of time, crafted around your deepest personal values.
Financial Independence
Transition seamlessly from active accumulation to peaceful distribution. Receive predictable, inflation-resistant monthly cash flow engineered to sustain your chosen lifestyle without liquidating core investments.
Family Confidence
Rest easy with the certainty that your spouse and heirs remain unconditionally shielded. Comprehensive health coverage, estate clarity, and emergency resilience mean you will never become a financial burden.
Retirement Dignity
Spend your days exploring passion projects, volunteering, or simply relishing peaceful mornings. Exercise complete command over how your time is spent, anchored by profound financial sovereignty.
CORE PLANNING PILLARS
A Retirement Plan Built
Around Your Life.
Six specialized disciplines synchronized into a single bespoke blueprint, engineered to protect your
purchasing power and preserve family prestige.
Inflation Preparedness
Dynamic asset allocation models with real-yield equity overlays designed to neutralize domestic living cost spikes across a 30-year horizon.
Healthcare Preparedness
Dedicated institutional medical reserves that protect primary family investments from escalating private medical care and critical treatments.
Guaranteed Monthly Cashflows
Precision cashflow architectures structured through sovereign instruments and annuity ladders, ensuring uninterrupted monthly income for life.
Legacy & Estate Succession
Seamless generational wealth succession structures, nominee alignments, and private family arrangements that safeguard family unity.
Tax-Smart Drawdowns
Optimized withdrawal sequencing across debt, equity gains, and statutory reserves to minimize lifetime capital gains tax exposure.
Family Milestone Ringfencing
Distinct capital earmarks dedicated to children's ambitions, weddings, and generational aspirations without interrupting your retirement runway.
Confidential, 1-on-1 consultations with zero product sales pressure.
OUR FIVE-STEP METHODOLOGY
Your Planning Journey
Starts Here.
A structured, fiduciary roadmap engineered to transform retirement ambiguity into absolute certainty - step by deliberate step.
Deep discovery into your ideal lifestyle, non-negotiable health priorities, and personal retirement timeline.
Rigorous simulations against high healthcare inflation, prolonged market downturns, and longevity scenarios.
Bespoke asset distribution across guaranteed annuity baselines, active wealth shields, and legacy structures.
Frictionless re-allocation of existing holdings with tax optimization, transparent reporting, and fiduciary care.
Scheduled bi-annual checkpoints and milestone audits ensuring your roadmap shifts as life and tax laws evolve.
Confidential, 45-minute retirement assessment : Zero sales pressure
PRIVATE WEALTH STEWARDSHIP • SINCE 2006
Meet Your Retirement
Planning Expert.
Pravin Kumar Jain has dedicated the past two decades to helping Indian families, business proprietors, and corporate executives build ironclad paths toward financial independence.
Starting his practice in 2006, Pravin rejected cookie-cutter sales pitches in favor of an institutional-grade, holistic planning philosophy. He views retirement not merely as an accumulation target, but as a deliberate defense against longevity risk, inflation, and market volatility.
Through personalized asset allocations, tax-efficient drawdown frameworks, and comprehensive healthcare reserves, Pravin ensures that when your active professional income stops, your standard of living and peace of mind never waver.
*Advisory & portfolio guidance volume under administration. Direct, fiduciary consultation.
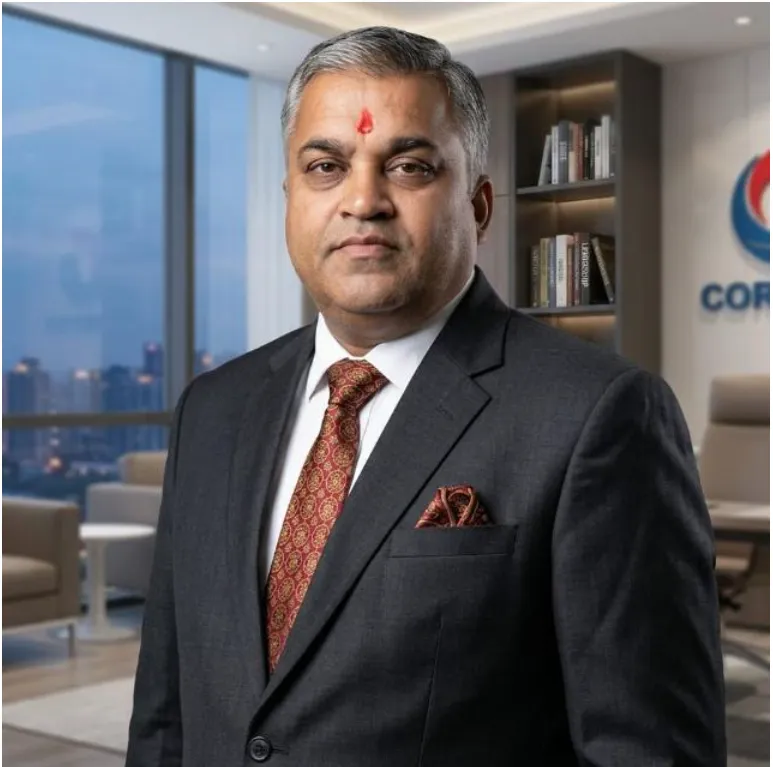
Pravin Kumar Jain
Principal Retirement Strategist • Fiduciary Advisor
Conflict-free personalized retirement modeling
Tailored wealth preservation for senior executives
Periodic rebalancing and tax-loss harvesting
VERIFIED CLIENT STORIES
Trust Is Built Through
Real Relationships.
Every retirement strategy we construct begins with patient listening, not product pitching. Discover how corporate leaders and business founders transformed complex wealth into sustainable, worry-free income streams.
100% Fee-only, fiduciary advisory with zero product bias
Over 180+ executive families guided toward financial autonomy
Tax-efficient drawdown plans designed for sustainable cashflow
Pravin transitioned our capital from erratic equity growth into steady monthly dividend distributions without degrading our core nest egg. The clarity regarding healthcare contingencies and generational legacy gives us absolute calm.

Unlike bank managers pushing high-commission insurance schemes, Pravin engineered an analytical plan accounting for real inflation, military pension tax optimizations, and our overseas family commitments.

Four years away from retirement, I felt paralyzed by fragmented mutual funds and unexercised ESOPs. Pravin consolidated everything into a lucid, tax-efficient drawdown blueprint with total fiduciary transparency.
FREE INITIAL RETIREMENT REVIEW
Understand Where You Stand
Before You Retire.
Retirement is not an age: it is a specific financial threshold. In this complimentary 45-minute confidential strategy session, we audit your existing assets against your anticipated lifestyle costs, healthcare contingencies, and tax liabilities so you know your exact retirement readiness score.
- Target Retirement Age vs. Corpus Longevity Stress-Test
- Post-Retirement Monthly Cash Flow & Expense Projections
- Comprehensive Critical Illness & Healthcare Reserve Modeling
- Withdrawal Sequencing & Tax Optimization Assessment
OBJECTIVE GUIDANCE
Frequently Asked
Questions
Retirement decisions are among the most consequential financial commitments of your lifetime. Here is transparent, educational clarity on the questions experienced professionals ask before engaging our fiduciary review.
Confidential • 1-on-1 Diagnostic • No Obligations
Is 45 or 50 too late to start structured retirement planning?
Not at all. In fact, between 45 and 52 you are typically in your peak earning years with major liabilities like home loans and early education costs stabilizing. Starting at 48 with an intentional asset allocation, systematic catch-up contributions, and active tax harvesting often produces a more resilient retirement strategy than a passive plan initiated a decade earlier.
Won't my EPF balance and company gratuity be sufficient for retirement?
EPF and gratuity provide a solid defensive bedrock, but they are rarely inflation-hedged for 25 to 30 years of post-retirement living. With realistic healthcare inflation compounding at 10-12% annually in India, relying solely on fixed-income provident funds risks corpus depletion within 12 to 14 years. We model multi-tier asset buckets so your money outlives your timeline.
How do we design a predictable retirement income if my earnings are irregular?
For business founders, senior consultants, and equity-compensated executives, lump-sum inflows dictate a specialized reserve mechanism. We structure a dedicated Cash Flow Buffer Account holding 18-24 months of operational expenses, allowing discretionary surplus to be channeled into long-term compounding instruments without forcing distress withdrawals during lean quarters.
How do you protect my retirement corpus against soaring medical and critical illness costs?
Corporate group mediclaim policies terminate the day you step down. We construct a multi-layer healthcare shield consisting of private super top-up coverage, specific critical illness reserves, and a dedicated medical emergency fund segregated from your primary monthly withdrawal stream, ensuring hospital bills never erode your baseline family income.
I already own residential real estate and bank fixed deposits. Why do I need a custom roadmap?
Physical property incurs high transaction friction, tenant vacancy risks, and tax inefficiencies, while fixed deposits suffer negative real returns once adjusted for 30% tax brackets and true inflation. Our fiduciary process does not replace existing assets; it optimizes their liquidity, reduces concentration risk, and synchronizes cash flow timing with your precise lifestyle goals.
How does Pravin's fiduciary advisory differ from commercial bank wealth managers or insurance agents?
Traditional bank relationship managers and insurance agents are incentivized by upfront product commissions and quota targets. Pravin operates on an unbiased, educator-led advisory methodology. We recommend bespoke portfolio architecture with zero bias toward proprietary financial products, prioritizing your capital preservation, net post-tax yield, and long-term dignity.
What happens if a significant market downturn occurs right before or during my early retirement?
This risk is called Sequence of Returns Risk. We insulate you by building a 3-Year Liquidity Moat before your retirement transition date. When equity markets experience volatility, your monthly income continues uninterrupted from cash equivalents and short-duration sovereign debt, allowing growth assets to fully recover without premature liquidation.
How does tax efficiency factor into retirement cash flows and monthly withdrawals?
Retirement is not just about compounding capital; it is about keeping what you withdraw. By engineering a calibrated sequence of Systematic Withdrawal Plans (SWP), tax-exempt interest bands, and long-term capital gains optimization, we frequently lower our clients' effective tax burden from 30%+ down to single digits during distribution phases.
Can my plan be adjusted if my personal priorities or target retirement age change later?
A retirement plan is a living framework, not a static binder. Life circumstances evolve: children relocate abroad, career transitions occur, or business opportunities emerge. We conduct structured bi-annual stress tests and rebalancing reviews to adapt asset allocation, withdrawal velocity, and legacy planning in lockstep with your changing life stage.
What is involved in the initial 1-on-1 retirement diagnostic session with Pravin?
The diagnostic is a focused 45-minute strategic audit. We analyze your existing asset allocation, projected inflation-adjusted liabilities, insurance adequacy, and current EPF/pension trajectory. You receive an objective Diagnostic Scorecard detailing specific vulnerability gaps, with clear actionable recommendations and zero sales pressure.
DECIDE YOUR TOMORROW TODAY
Your Future Is Too Important
to Leave to Chance.
The lifestyle and independence you envision for your retirement require disciplined strategy, not speculative hope.
Partner with Pravin to build a protected, tax-efficient legacy that safeguards your family for decades ahead.
DIRECT LINE: +91 9993720297 | ADVISORY DESK: [email protected]
Pravin Retirement Planning
Bespoke Wealth Preservation and Comprehensive Retirement Fiduciary Advisory for Indian Executives, Business Owners, and Global NRIs.
Direct Advisory Desk: +91 (022) 6124-8800 | Confidential Inquiries: [email protected] |
REGULATORY MANDATE & STATUTORY RISK DISCLAIMER
Pravin Retirement Planning operates strictly as an independent fee-only fiduciary wealth practice. Professional registration granted by SEBI and credentials from NISM in no way guarantee investment performance or provide assured returns. Financial longevity models, corpus growth estimates, and retirement readiness scores generated on this portal are designed exclusively for analytical modeling and educational insight. Capital allocated across mutual funds, debt structures, equities, and sovereign assets remains subject to market volatility. Clients are advised to carefully examine scheme information memoranda and evaluate individualized risk tolerances prior to execution. Nothing on this website constitutes an offer, solicitation, or contractually binding investment guarantee. Individual tax consequences remain subject to prevailing provisions of the Indian Income Tax Act, 1961; clients must seek advice from an independent chartered accountant regarding specific fiscal obligations.


© 2026 Pravin Retirement Planning. All rights reserved. Dedicated to Wealth Protection, Income Longevity, and Legacy Preservation.